
What is Factor Investing: Definition and Overview
Factor investing is a quantitative strategy involving the selection of securities based on measurable characteristics (factors) that are historically linked to higher returns.
Unlike traditional stock picking, this approach uses data and research to guide investment choices, helping investors target specific sources of risk and reward across a portfolio.
Origins of Factor-Based Investing
The concept of factor investing traces back to the development of the Capital Asset Pricing Model (CAPM) in the 1960s. The CAPM, introduced by economists like William Sharpe and John Lintner, aimed to explain a security’s expected return based on its sensitivity to overall market risk, known as beta. According to the CAPM, market beta was the sole driver of returns, while any deviation was considered company-specific or “alpha.”
However, real-world data soon revealed that certain stock characteristics, such as company size or valuation, could consistently explain these differences in returns. This led to the rise of models like Stephen Ross’s Arbitrage Pricing Theory (APT) in 1976, which proposed that multiple economic factors influence asset prices, though it didn’t define which ones.
Later in 1992, Eugene Fama and Kenneth French advanced the field with their Three-Factor Model, which better accounted for historical returns, laying the groundwork for modern factor investing. Over time, additional factors were identified, giving rise to today’s data-driven factor investment strategies.
Factor Investment vs Passive and Active Investment
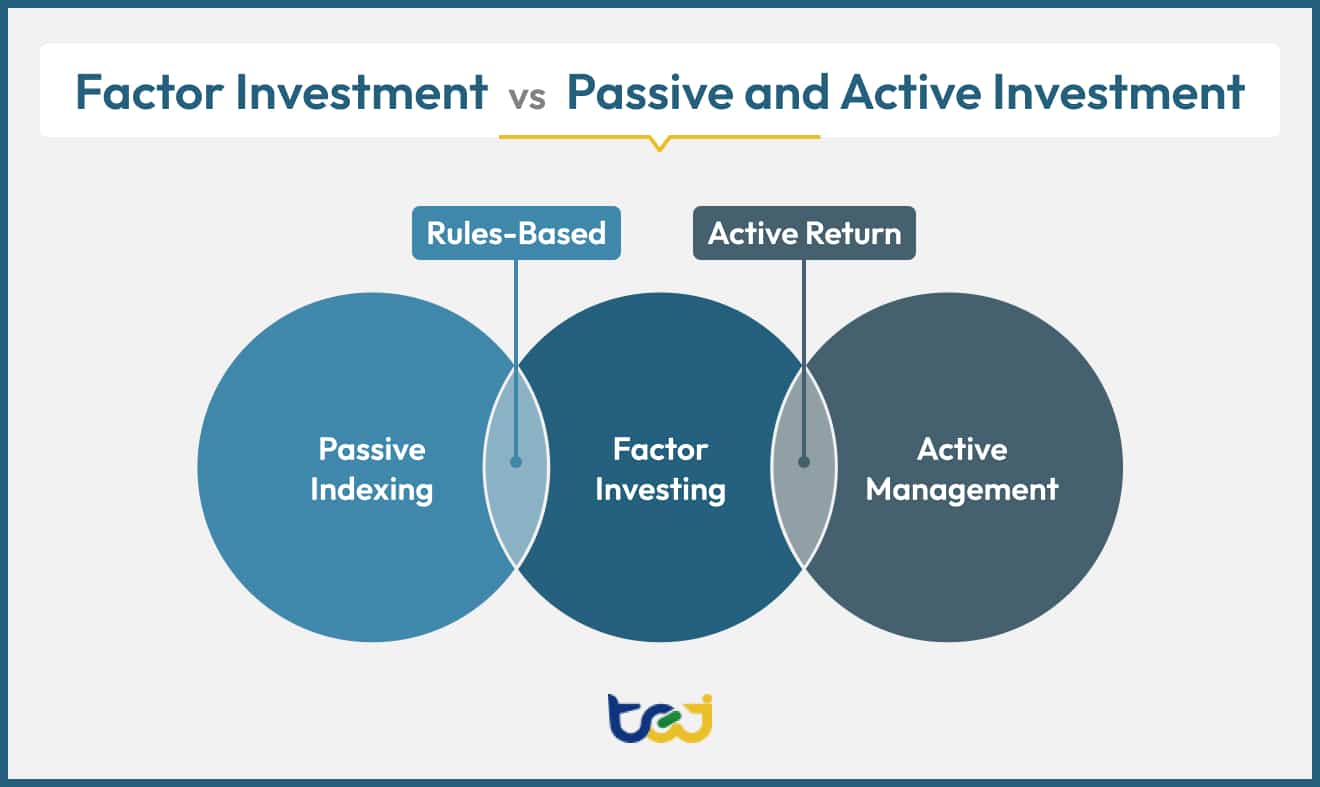
Factor investing is often described as a middle ground between passive and active investing.
Passive strategies aim to replicate market performance by tracking broad indexes with minimal trading. On the other hand, active investing involves frequent stock selection and timing decisions to outperform the market.
Like passive investing, factor investing is typically rules-based, transparent, and cost-efficient, using predefined criteria to construct portfolios. It also shares traits with active investing by selectively targeting factors to seek excess returns and manage risk more strategically. This approach offers a systematic way to pursue alpha while maintaining the efficiency of a passive structure.
Why Do Investment Factors Work?
Investment factors may generate persistent differences in risk and return for several reasons.
One explanation is risk compensation: investors may earn higher expected returns for holding securities exposed to certain risks, such as smaller or financially distressed companies.
Another explanation comes from investor behavior. Biases such as overreaction, underreaction, and herding can cause securities to become temporarily mispriced, helping explain patterns such as value and momentum.
Market structure and institutional constraints may also contribute. For example, investment mandates, benchmarking requirements, liquidity constraints, or limits on arbitrage can prevent mispricing from disappearing immediately.
However, not every characteristic that performs well in historical data represents a reliable investment factor. A meaningful factor should generally have a reasonable economic rationale, consistent empirical evidence, and robustness across different periods or markets rather than relying solely on attractive backtest results.
Why are Factor Portfolios Important?
Different factors respond uniquely to changing market conditions, so combining them helps improve diversification to reduce reliance on a single return source, even within equity portfolios.
By targeting characteristics linked to strong historical performance, factor investing can also help manage downside risk and increase the chance of consistent returns. Ultimately, factor-based strategies offer a structured, data-informed way to strengthen portfolio performance across various market cycles.
You can also dive deeper into this through TEJ’s factors research guides here:
Types of Factors
There are 2 main categories of investment factors, including macroeconomic factors and style factors. Let’s look at these categories and their examples below.
Macroeconomic Factors
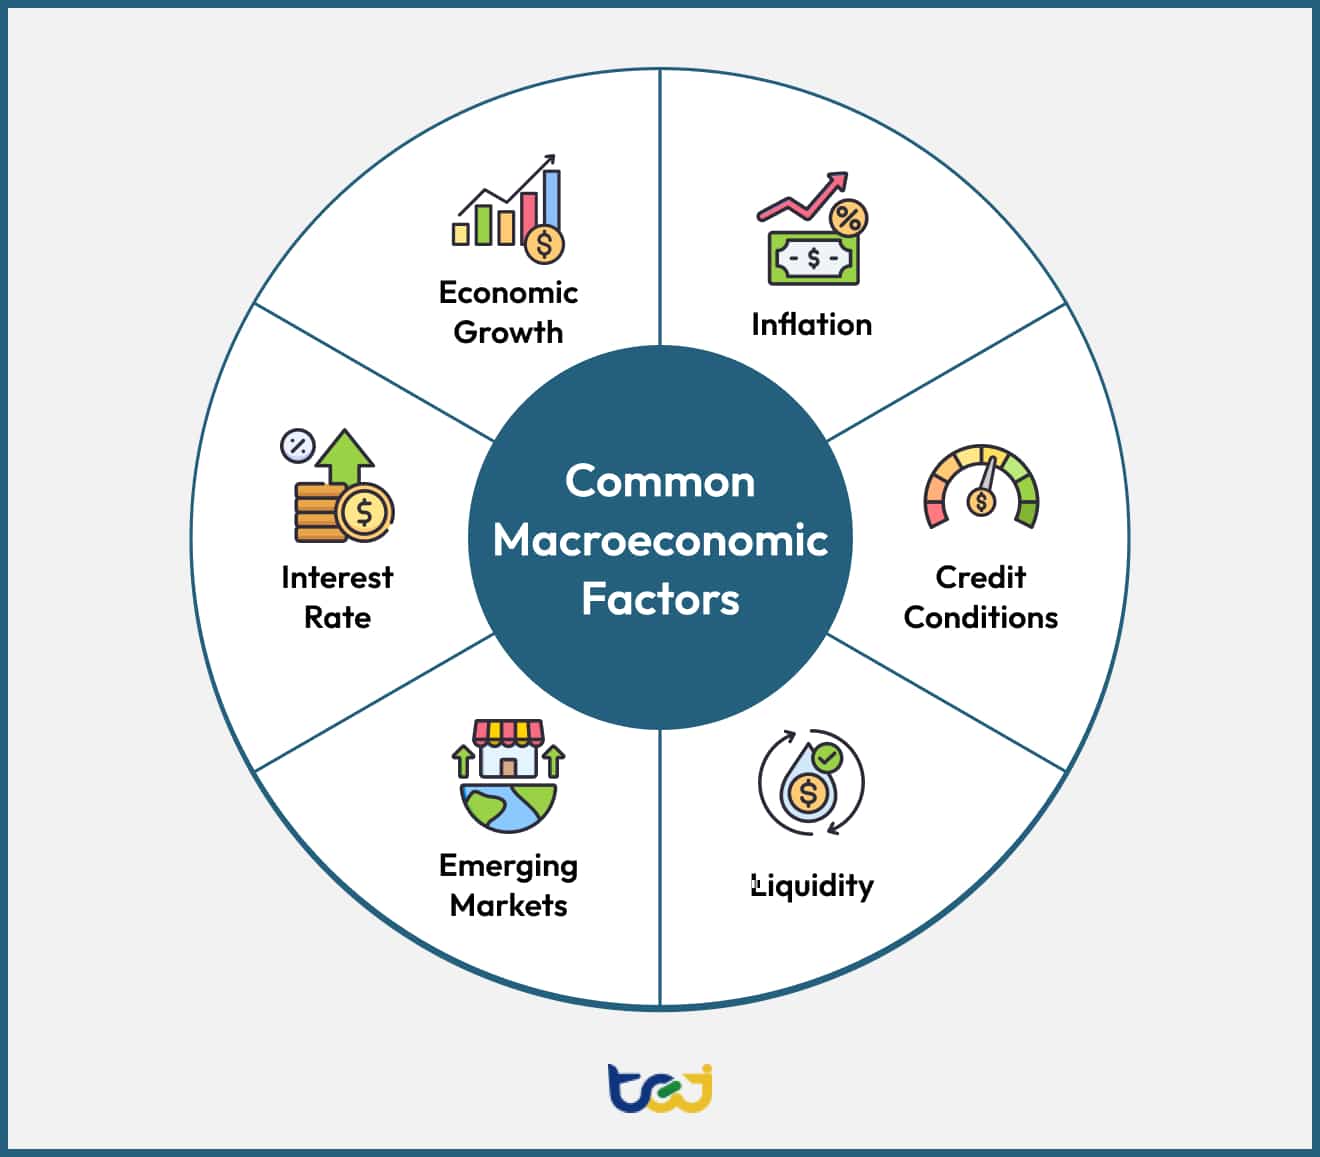
Macroeconomic factors represent broad, systemic risks and opportunities that influence returns across entire asset classes, not just individual securities. They are tied to the overall health and direction of the global economy. Examples include:
Economic Growth
Economic growth reflects the overall health of the economy. Strong growth generally boosts corporate earnings and stock prices, while a slowdown can lead to reduced profits and market declines.
Inflation
Inflation measures the rate at which prices for goods and services rise. Higher inflation erodes purchasing power and can pressure corporate margins, impacting equity and bond markets. Low and stable inflation tends to support market growth.
Interest Rate
Interest rate changes influence borrowing costs for companies and consumers. Higher rates can slow growth and pressure stock prices, while lower rates typically boost market activity.
Credit Conditions
Credit conditions gauge the availability and cost of borrowing in the market. Tight credit can increase default risks and reduce corporate expansion, while easier credit can support growth.
Currency / Exchange Rates
Exchange rate movements influence trade, corporate earnings, asset valuations, and cross-border investment returns. A stronger domestic currency can reduce the value of overseas earnings and make exports more expensive, while a weaker currency can increase import costs and inflationary pressure. As a result, currency fluctuations can affect performance across equity, bond, and international markets.
Style Factors
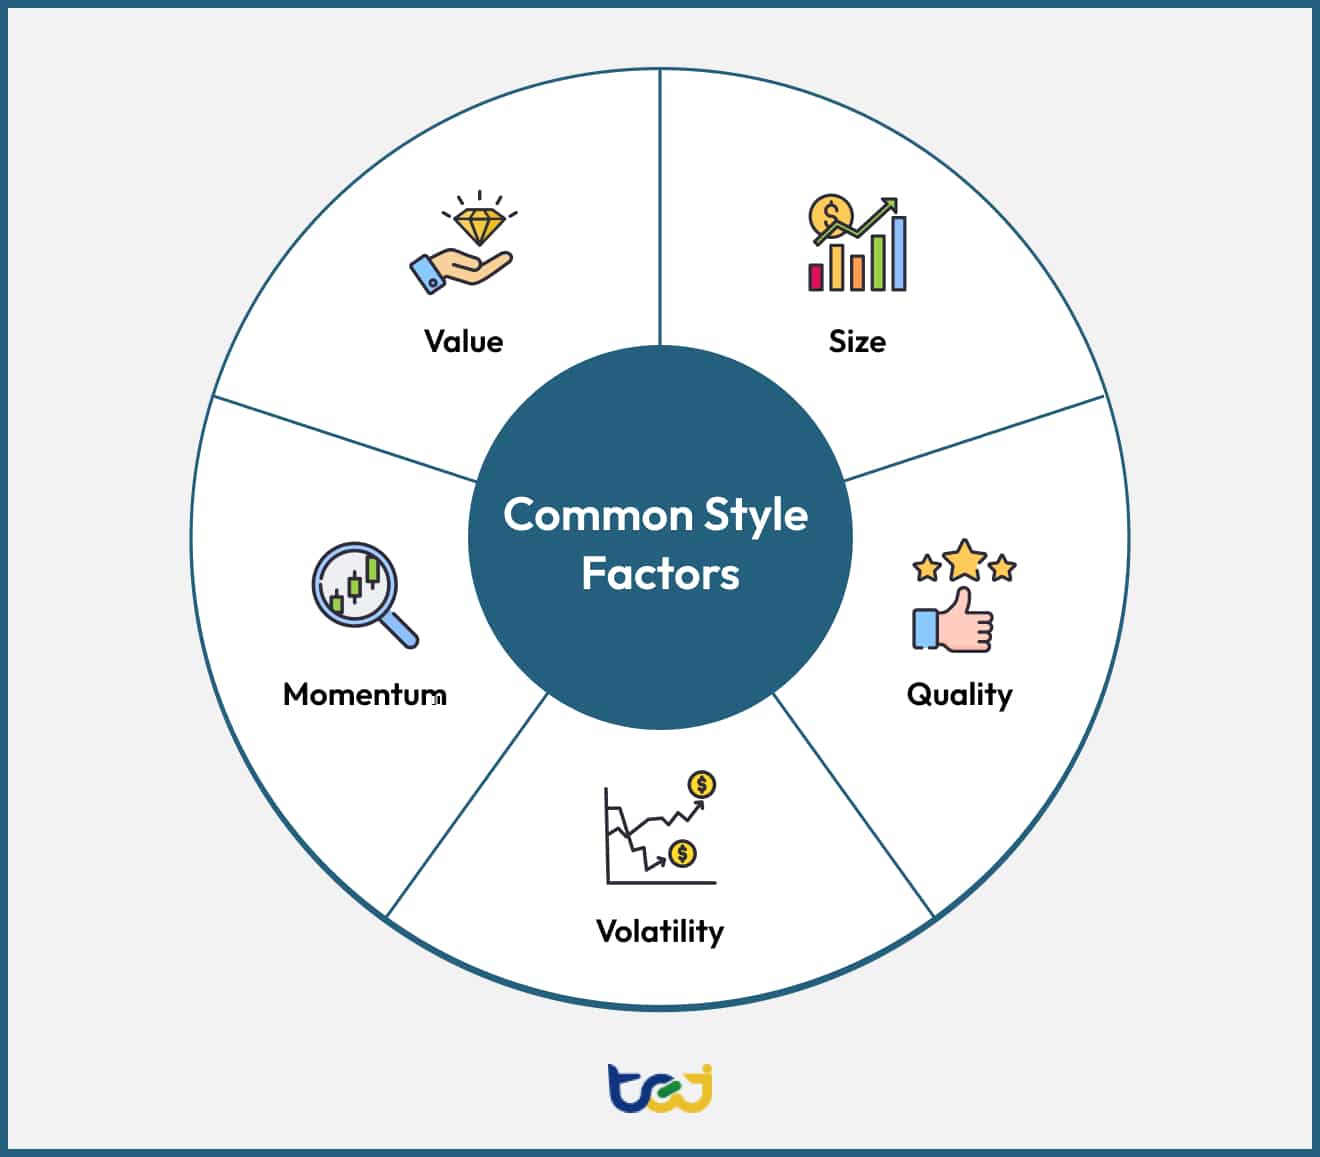
Style factors explain the sources of risk and return within asset classes by focusing on measurable company-level characteristics. They allow investors to systematically tilt their portfolios towards companies exhibiting these traits. Examples include:
Value
Value factors focus on buying securities that appear undervalued relative to their fundamentals, using metrics like price-to-earnings (P/E) or price-to-book (P/B) ratios. Historically, undervalued companies have delivered stronger long-term returns as their market price gradually reaches their true value.
Size
The size factor reflects a company’s market capitalization. Small-cap stocks (those from companies with relatively smaller market capitalization) often outperform large-cap stocks over time because they may have higher growth potential.
- Additional Resource: Starting from Robert Gaddie’s Stock-Picking Method: Searching for Small-Cap Growth Dark Horses in the Taiwan Stock Market
Momentum
Under the idea that trends can persist in the short term, momentum is measured over three- to twelve-month periods, helping investors target stocks with strong recent performance and vice versa.
- Additional Resource: The Momentum Strategy — Does the Trend Remain?
Quality
Quality factors identify financially sound companies with strong balance sheets, stable earnings, and high returns on equity or assets. These companies often perform well in volatile markets.
Volatility
Volatility factors focus on price stability. Low-volatility stocks, which experience fewer price swings, have historically provided better risk-adjusted returns than their high-volatility counterparts.
Nevertheless, identifying effective factors can be challenging due to inconsistent definitions, data limitations, and the “factor zoo” phenomenon, where many proposed factors lack true predictive power. Hence, disciplined methodologies and reliable databases, such as TEJ’s factor library, become essential to avoid bias and errors in investment decisions. It covers nine factor categories, including dividend yield, value, and growth, enabling efficient factor investing.
Liquidity
Liquidity measures how easily assets can be bought or sold without affecting prices. Low liquidity can magnify volatility and make it harder for investors to exit positions during market stress. In contrast, highly liquid markets allow for more stable portfolio management.
| Style Factor | What It Focuses On | Common Indicators | Investment Rationale |
| Value | Securities trading at relatively low prices compared with their fundamentals | P/E ratio, P/B ratio, earnings yield | Undervalued securities may offer higher long-term return potential as valuations normalize |
| Size | Company size based on market capitalization | Market capitalization | Smaller companies may offer greater growth potential and have historically earned a size premium |
| Momentum | Strength and persistence of recent price performance | 3- to 12-month historical returns | Recent price trends may persist over the short to medium term |
| Quality | Financial strength, profitability, and earnings stability | ROE, ROA, profitability, earnings stability, leverage | Financially strong companies may be more resilient and deliver more consistent performance |
| Volatility | Stability of security price movements | Historical volatility, beta | Lower-volatility securities may provide more favorable risk-adjusted returns |
| Liquidity | Ease of buying or selling a security without significantly affecting its price | Trading volume, turnover ratio, bid-ask spread | More liquid securities are generally easier and less costly to trade, while lower liquidity may increase trading difficulty and price volatility |
Common Factor Investing Strategies
Investors can implement factor investing in several ways depending on their risk tolerance, time horizon, and portfolio objectives. The three most common approaches are single-factor, factor-timing, and multifactor strategies, so let’s delve deeper into them:
Single-Factor Strategy
A single-factor strategy involves constructing a portfolio that focuses on exposure to just one specific factor at a time, such as value, momentum, or low volatility.
With this approach, investors can capture the long-term risk premium associated with that particular factor. It is also relatively straightforward to understand and implement, often incurring lower transaction costs than more complex strategies.
Still, the performance of single-factor investments can be highly cyclical, with potential underperformance lasting years. This makes them better suited for investors with patience and strong conviction over a long-term horizon.
Factor-Timing Strategy
Factor timing attempts to rotate among factors based on expected market conditions, seeking to capture each factor’s outperformance at the right time, while letting go of those that are expected to lag.
While a well-executed timing strategy could theoretically deliver exceptional returns, the approach requires highly accurate predictions and involves significant turnover costs. Missing just a few key periods of factor outperformance can severely hurt results, making this strategy very difficult for most investors.
Multifactor Strategy
A multifactor strategy combines exposure to several distinct factors simultaneously within a single portfolio, leveraging the often-low correlations between them.
This diversification helps reduce reliance on any single factor, smoothing returns and mitigating periods of underperformance. In turn, multifactor strategies generally offer a better balance of risk and return compared to single-factor or timing approaches.
However, multifactor strategies can be more complex to construct and manage than single-factor portfolios. This is why investors have to rely on sophisticated analysis and robust data to determine the optimal weighting and rebalancing frequency for multiple factors.
Risks and Limitations of Factor Investing
Factor cyclicality
No single factor consistently outperforms. Several classic value-related factors underperformed during much of the 2010s, a decade dominated by growth-oriented markets, although factor performance varied across definitions and regions.”; momentum can reverse sharply when market regimes shift. Investors should expect multi-year periods of underperformance even from well-documented factors.
The factor zoo problem
Researchers have proposed hundreds of factors, but most lack true predictive power once tested out-of-sample. A 2016 paper by Harvey, Liu, and Zhu identified over 300 published factors. Many may reflect data mining, multiple testing, or weak out-of-sample robustness rather than reliable return premia.
Crowding risk
As more capital flows into factor strategies, the premium can compress. High factor crowding raises the risk of sharp drawdowns when investors simultaneously unwind similar positions.
Implementation costs
Transaction costs, taxes, and rebalancing friction can erode theoretical factor premiums — especially for high-turnover strategies like momentum.
Despite these limitations, factor investing remains a widely used approach when applied with disciplined methodology and a long-term perspective.
How to Implement Factor Investing
There are several ways investors can implement factor investing strategies, depending on their level of expertise, resources, and investment goals. From simple, low-cost solutions to advanced quantitative approaches, each method offers different levels of control, flexibility, and complexity.
Each method offers different trade-offs between simplicity, cost, and control, making it important to choose an approach that aligns with your investment objectives.
Factor ETFs
Factor ETFs are the most accessible way to gain exposure to common factors such as value, momentum, quality, and size. These funds are designed to track specific factor-based indexes and provide instant diversification with relatively low costs.
They are especially suitable for beginners or investors who want a straightforward, passive approach to factor investing without the need for complex analysis or portfolio construction.
Smart Beta Indexes
Smart beta strategies use rules-based methodologies to tilt portfolios toward specific factors. Unlike traditional market-cap-weighted indexes, smart beta indexes systematically adjust weightings based on predefined criteria such as volatility, fundamentals, or factor exposure.
These strategies are widely adopted by institutional investors as benchmarks or investment vehicles, offering a balance between passive investing and active strategy design.
Quantitative Factor Models
Quantitative factor models involve constructing investment strategies using financial data, statistical techniques, and systematic rules. This approach allows investors to combine multiple factors, optimize portfolio allocation, and refine strategies based on historical performance and risk characteristics.
However, successful implementation depends heavily on data quality and methodology. Issues such as look-ahead bias, survivorship bias, and inconsistent accounting standards can significantly distort backtesting results and lead to misleading conclusions.
FAQs
What is factor investing?
Factor investing is a systematic investment approach that selects securities based on measurable characteristics, or factors, associated with differences in risk and return. Instead of choosing stocks primarily through individual judgment, investors use predefined rules and data to target factors such as value, momentum, quality, size, or volatility.
What are the most common factors used in factor investing?
Common style factors include value, size, momentum, quality, and volatility. Investors may also consider broader macroeconomic factors such as economic growth, inflation, interest rates, credit conditions, and liquidity. Different factors can perform differently across market environments, which is one reason investors may combine several factors within a portfolio.
How is factor investing different from active and passive investing?
Factor investing sits between traditional passive and active investing. Like passive investing, it generally follows systematic, transparent rules rather than relying entirely on individual stock-picking decisions. However, like active investing, it intentionally tilts a portfolio toward selected characteristics in an effort to improve returns, manage risk, or achieve specific investment objectives.
What is the difference between single-factor and multifactor investing?
Single-factor investing focuses on one characteristic, such as value or momentum, providing concentrated exposure to a specific return driver. Multifactor investing combines several factors within the same portfolio. This can improve diversification and reduce dependence on any one factor, although constructing and rebalancing a multifactor strategy can be more complex.
Is smart beta the same as factor investing?
Not exactly. Factor investing is the broader concept of targeting systematic drivers of risk and return. Smart beta is one way to implement factor investing, usually through transparent, rules-based indexes that weight securities according to factors such as value, quality, or low volatility rather than simply by market capitalization.
What are the main risks of factor investing?
Factor investing does not guarantee market outperformance. Individual factors can underperform for long periods, while crowded strategies may experience sharp reversals. Investors should also consider transaction costs, rebalancing costs, factor selection, and the quality of the underlying data. For quantitative strategies, problems such as look-ahead bias and survivorship bias can also distort backtesting results.
TEJ: Data Solutions for Factor Investing Models
TEJ stands as a trusted financial data provider known for delivering accurate, research-ready solutions to support advanced investment strategies.
Engineered for factor investments, our Factor Library is a fully point-in-time database covering over 100 factors across nine major categories: Momentum, Dividend Yield, Value, Growth, Quality, Liquidity, Volatility, Size, and Sentiment. Built on academic foundations and localized for Taiwan’s market, it helps investors streamline research and improve backtesting reliability for enhanced portfolio construction.
Explore the TEJ’s Factor Library today and discover how it integrates seamlessly with our Quantitative Investment Database for even greater insight and performance.